Round Rock Business logo representing business funding, payment processing, and local business services in Round Rock Texas

Business Funding Options for Pflugerville, TX Businesses

đź’° Explore My Funding Options

Start With a Few Quick Questions  No Obligation

Explore Business Funding and Working Capital Options Based on Your Business Profile.

Independent funding broker • Application continues securely through a third-party funding platform

Business Line of Credit for Pflugerville Businesses: What Owners Should Know

Running a business rarely means that income and expenses arrive on the same schedule. A Pflugerville business may complete a project weeks before receiving payment, need inventory ahead of a busy period or encounter an unexpected repair that cannot wait for the next revenue cycle.

A business line of credit may provide eligible businesses with a flexible way to address certain short-term needs. Unlike receiving one lump sum that immediately begins a fixed repayment schedule, a revolving line generally allows an approved business to draw available funds when needed, repay the amount used and potentially access those funds again.

That flexibility can be useful, but it does not make every line of credit suitable for every business. Provider requirements, draw fees, interest, repayment frequency and other terms can vary. Before applying or accepting an offer, Pflugerville business owners should understand how the product works and compare the potential cost with the business purpose it is intended to support.

Business owners who are still comparing broader possibilities can first review the available Pflugerville business funding options.
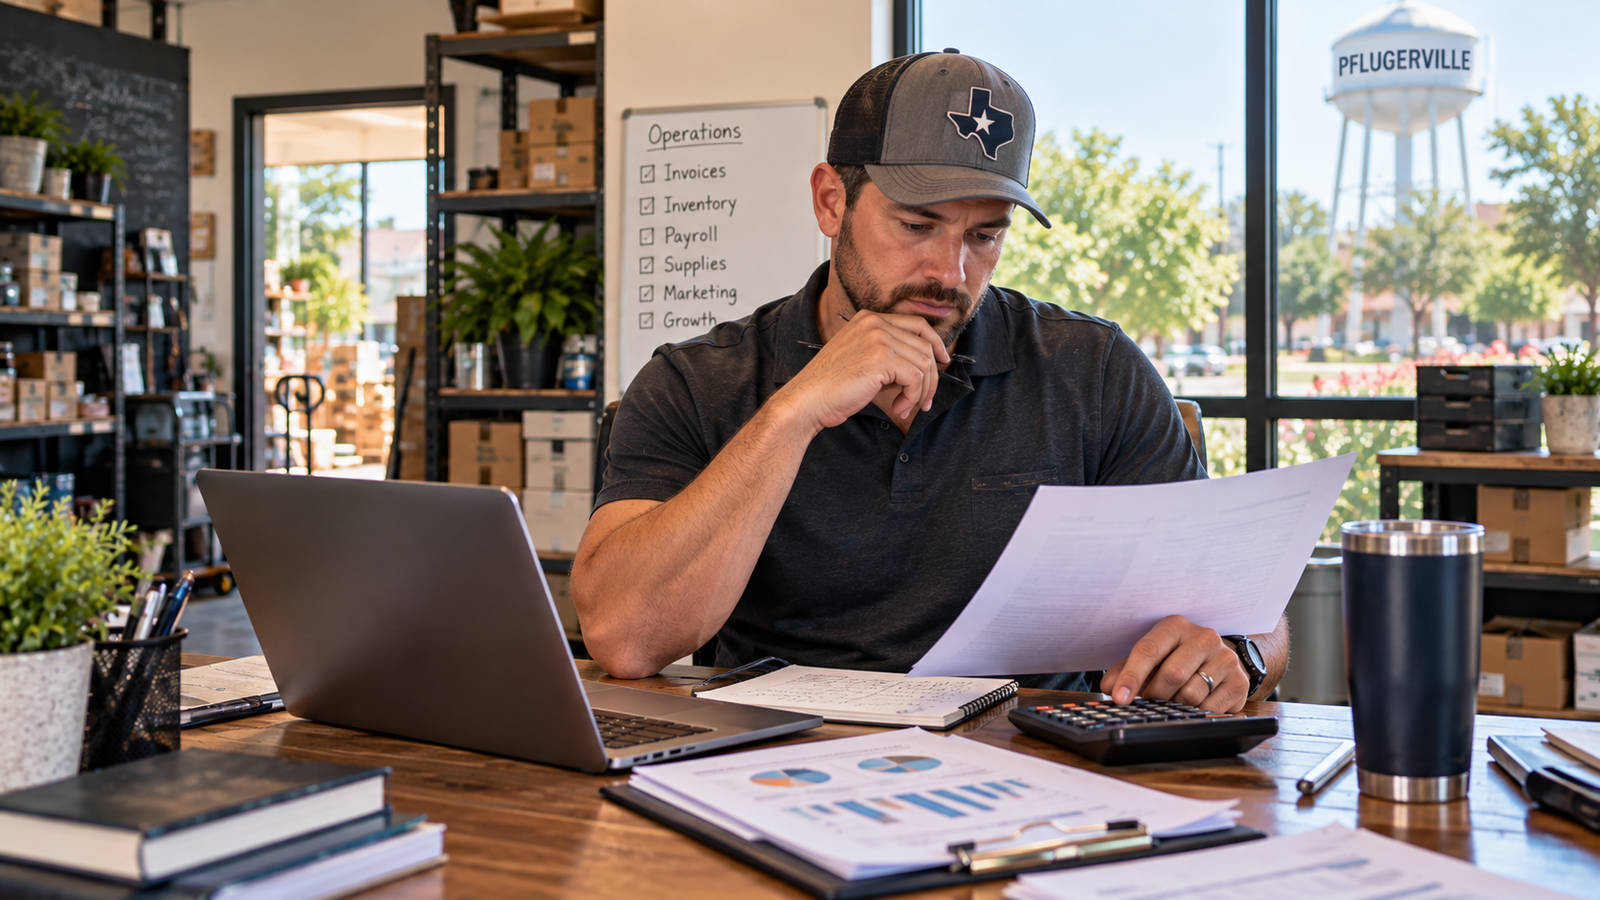
Pflugerville small business owner reviewing cash flow and upcoming operating expenses

What Is a Business Line of Credit?

A business line of credit is a form of revolving financing with an established credit limit. If approved, the business may draw some or all of the available amount according to the provider’s terms. As the drawn balance is repaid, part of the limit may become available again.

For example, a business approved for a $40,000 line might initially draw $10,000 for inventory. The remaining availability would generally stay unused. As the business repays the drawn amount, its available credit may increase again, subject to the agreement and the account remaining in good standing.

This differs from receiving a $40,000 term-financing amount all at once. With a line of credit, the business generally pays financing costs based on the amount drawn rather than the entire approved limit. However, some products may also carry draw fees, maintenance fees, balance fees or minimum-use requirements. Owners should examine the complete agreement instead of relying only on a stated rate or credit limit.

When Might a Pflugerville Business Consider a Line of Credit?

A line of credit is generally better suited to identifiable short-term or recurring needs than to covering an ongoing financial problem with no repayment plan. Potential uses may include..

Purchasing inventory before a predictable sales period
Covering payroll while waiting for customer invoices
Managing timing differences between receivables and expenses
Addressing an unexpected repair or replacement
Purchasing supplies for a confirmed project
Supporting a temporary increase in operating activity

Consider a Pflugerville contractor who must purchase materials before receiving a scheduled customer payment. A draw from an available line could help bridge that timing gap, but the owner should first determine when the customer payment is expected and whether it will comfortably cover the required repayment.

A line should not automatically be treated as additional revenue. Every draw creates an obligation. Before using one, the owner should identify the expense, expected business benefit, repayment source and effect of the required payments on future cash flow.

How Is a Line of Credit Different From Other Funding Options?

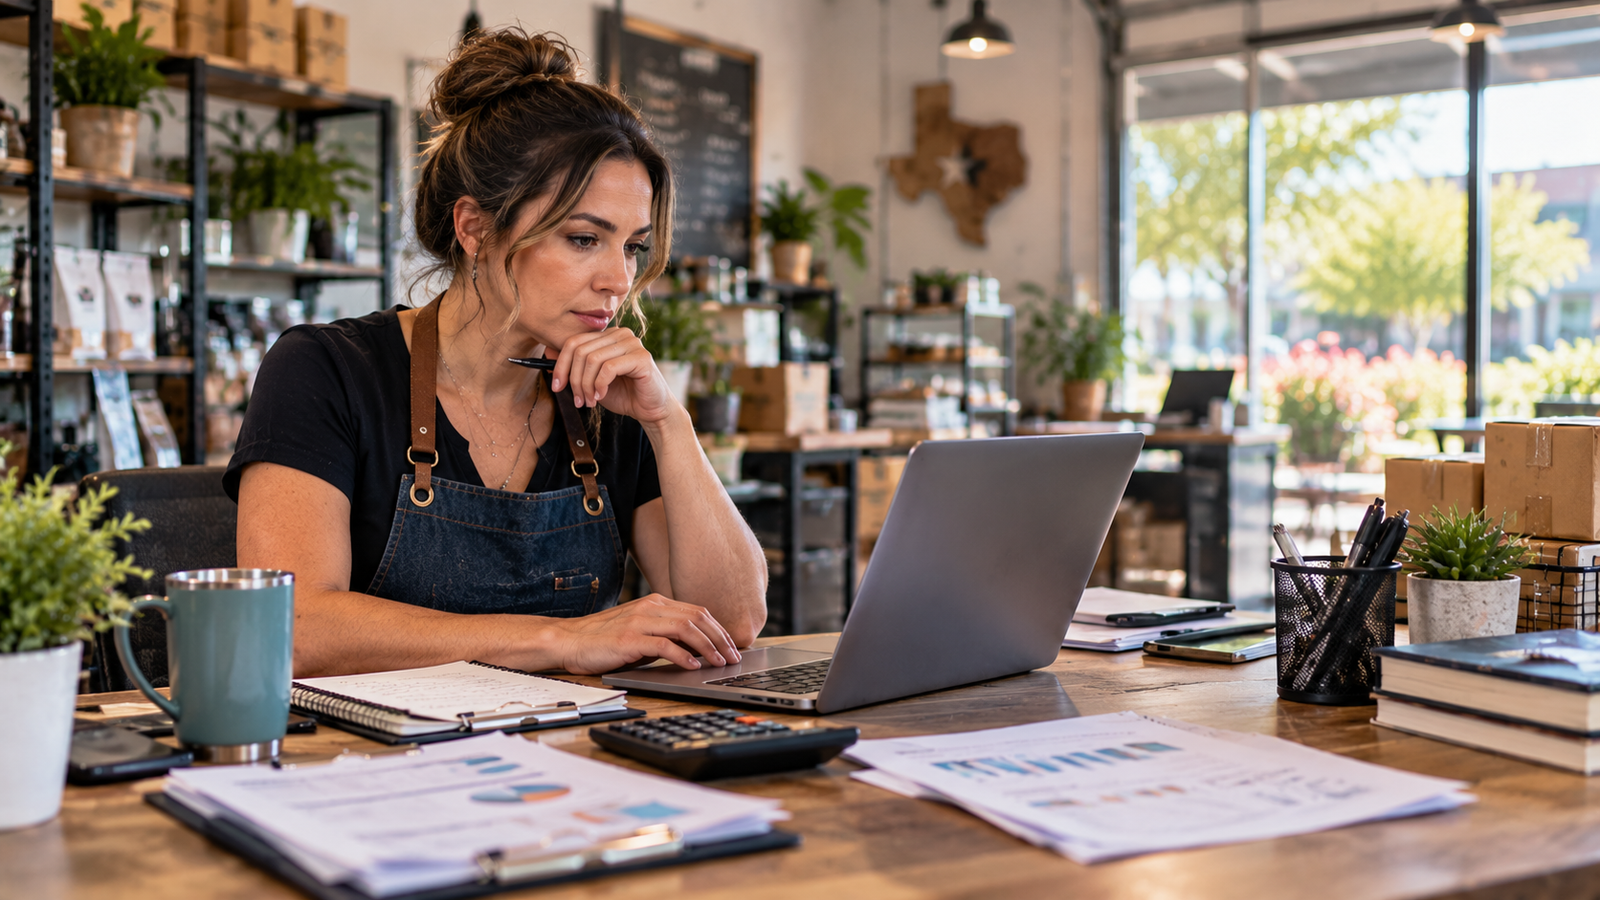
Pflugerville small business owner comparing invoices, inventory needs and cash flow
The primary difference is flexibility. Term financing usually provides a single amount followed by a defined repayment period. A business line of credit allows repeated draws up to an available limit, subject to the provider’s conditions.

Equipment financing serves another purpose. It is generally connected to purchasing a particular vehicle, machine, technology system or other business asset. Owners planning a specific equipment purchase can review the separate guide to equipment financing for Pflugerville businesses.

A line of credit may make more sense when the exact timing or amount of an expense is uncertain. Term or equipment financing may be more appropriate when the business has a clearly defined, one-time purchase. The correct comparison should include total cost, payment frequency, collateral requirements, draw conditions and how long the business expects to carry the balance.

The U.S. Small Business Administration also describes several distinct revolving programs for short-term, cyclical and working-capital needs. These SBA programs operate under their own eligibility and lender requirements and should not be confused with a general commercial line of credit.

Costs and Repayment Terms to Review Carefully

The flexibility of a business line of credit should be evaluated alongside its complete cost. Two providers may offer similar credit limits while applying different rates, fees, payment schedules and draw conditions.

Before accepting an offer, review..

The Interest Rate or Other Financing Cost?
Whether Costs Apply Only To The Amount Drawn?
Draw, Origination, Maintenance Or Balance Fees?
Weekly Or Monthly Payment Requirements?
The Time Allowed To Repay Each Draw?
Prepayment Conditions?
Late-Payment And Insufficient-Funds Fees?
Whether The Rate Is Fixed Or Variable?
Conditions That Could Reduce Or Suspend Availability?

Payment frequency deserves particular attention. A weekly payment may affect cash flow differently than a monthly payment, even when the advertised cost appears manageable. Estimate the payment’s effect during both strong and slower revenue periods.

Ask the provider to explain anything that is unclear and retain a copy of the complete agreement. The available limit matters, but the more important question is whether the business can use and repay a draw without creating another cash-flow problem.

Questions to Ask Before Drawing Funds

Approval does not automatically mean the entire available amount should be used. Before making a draw, the owner should be able to answer several practical questions:

1. What specific business expense will the draw cover?
2. Is the expense expected, urgent or discretionary?
3. How could it support revenue, efficiency or continuity?
4. What business income is expected to repay it?
5. When should that income arrive?
6. Could the business manage the payments if revenue were delayed?
7. What is the estimated total cost of the draw?
8. Is there a less expensive way to address the need?

Consider a local service business preparing for several confirmed projects. A limited draw for supplies could be tied to expected customer payments. That is different from repeatedly drawing funds to cover an operating shortfall without identifying why the shortfall continues.

A revolving line can make repeated access convenient. That same convenience makes it important to establish internal rules about when funds may be drawn, how much may be used and how repayment will be monitored.
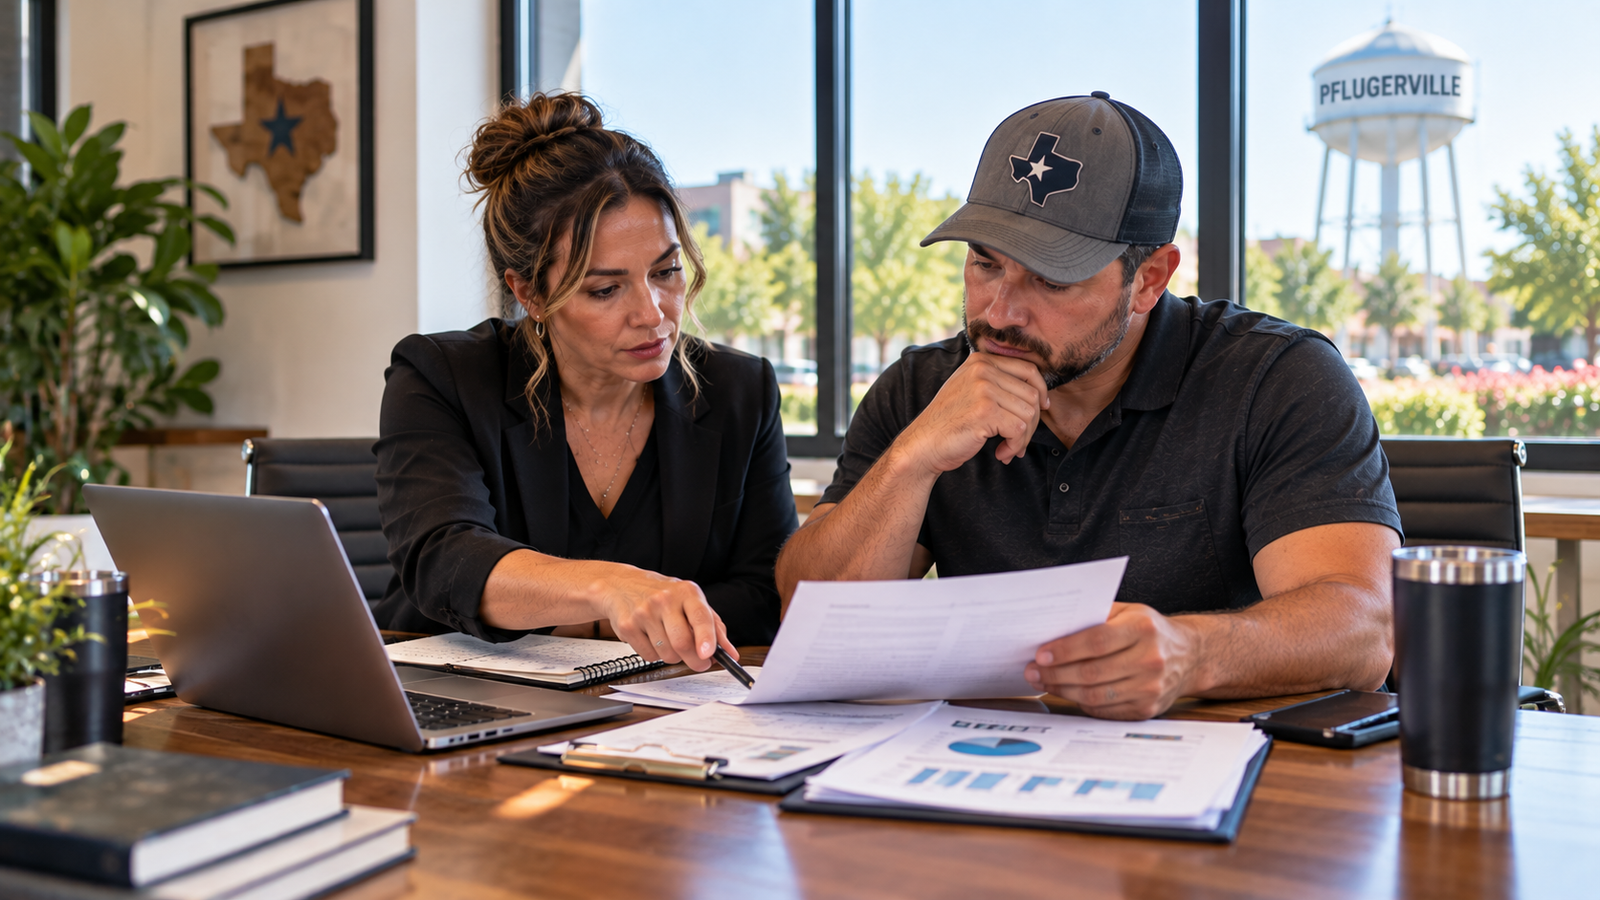
Pflugerville small business owner reviewing line of credit repayment terms with an adviser

How to Prepare Before Exploring a Business Line of Credit

Organization can make it easier to evaluate a potential offer and provide information requested during a review. Requirements differ, but owners may benefit from gathering:

"Recent Business-Bank Statements"
"Current Revenue Information"
"Accounts Receivable and Payable Records"
"A List Of Existing Financial Obligations"
'Basic Profit-and-Loss Information"
"Business Formation and Ownership Documents"
"Identification For Applicable Owners"
"A Clear Explanation Of The Intended Use"

Review the records for accuracy before submitting them. Unexplained deposit changes, frequent negative balances or conflicting information may require additional clarification.

Owners should also compare more than the possible credit limit. Review the proposed payment, total potential cost, access period and circumstances under which future draws could become unavailable.

Businesses interested specifically in SBA-backed financing can use SBA Lender Match to explore participating lenders. SBA Lender Match is a separate lender-connection resource, not a Round Rock Business application, and it does not guarantee that a business will be matched or offered financing.
Connect the Funding Decision to the Larger Business Plan
A line of credit should support an identifiable business objective rather than replace planning. That objective might involve managing invoice timing, purchasing seasonal inventory, completing a contracted project or handling a necessary operating expense.

The owner should consider what happens after the immediate need is addressed. Will the expense help the business serve customers, complete work or operate more efficiently? Will the resulting cash flow arrive before repayment creates pressure elsewhere?

Funding and customer acquisition can also affect one another. Borrowing to support growth is less useful when the business has no plan for attracting or retaining customers. Pflugerville owners evaluating that side of the business can review these Pflugerville Local SEO resources.

Business owners comparing additional regional information can also visit the Central Texas Business Funding Resource Hub. The goal is not simply to obtain access to funds. It is to determine whether a potential obligation fits the business’s present need, expected cash flow and broader operating plan.

Frequently Asked Questions About Business Lines of Credit in Pflugerville

Can a small business in Pflugerville get a business line of credit?

Some established small businesses may qualify, but eligibility depends on the applicable provider and the business’s overall profile. Revenue, time in business, credit history, banking activity and existing obligations may be considered. Submission of an application does not guarantee approval.

Do businesses pay interest on the entire approved limit?

With many revolving lines, financing costs apply to the amount drawn rather than the full available limit. However, some products may include draw, maintenance, balance or other fees. Review the complete agreement for the specific cost structure.

How much of a business line of credit should an owner use?

The appropriate amount depends on the identified expense, expected benefit and ability to repay. An approved limit should not automatically be treated as a spending target. Owners should draw only what the business can reasonably use and repay.

Can a newer business qualify?

Possibly, but many line-of-credit programs require an established operating history. Requirements differ between providers. Newer businesses may encounter different potential funding options, costs or limits.

Is a line of credit the same as equipment financing?

No. A line of credit may support various short-term or recurring needs, while equipment financing is generally connected to purchasing a particular business asset. Owners planning a specific purchase can review the guide to equipment financing for Pflugerville businesses.

Will exploring a line of credit affect personal credit?

That depends on the provider and stage of the process. Some initial reviews may use a soft credit inquiry, while a later application or offer may involve a hard inquiry. Ask which type of inquiry will be performed and when before authorizing a credit review.

Make the Decision Based on More Than the Credit Limit

A business line of credit may give an eligible Pflugerville business greater flexibility when expenses and income do not arrive on the same schedule. Its usefulness, however, depends on the purpose of each draw, the complete cost and the business’s ability to manage repayment.

Compare potential options carefully. Review the rate, fees, payment frequency, draw rules and repayment conditions. Most importantly, connect the obligation to a specific business need and a realistic repayment source.

Continue Building Your Pflugerville Business Funding Knowledge

Access to flexible funds is only one part of a business funding decision. When the need involves purchasing machinery, replacing aging equipment or adding essential technology, the structure of the potential financing may look different.

Equipment financing is generally connected to a particular business asset, while a business line of credit may support a wider range of short-term or recurring needs. Understanding that distinction can help an owner compare the purpose, potential cost and repayment structure of each option.

Our next Pflugerville guide explores how equipment financing generally works, what an applicable provider may review and which questions business owners should consider before moving forward.

Ready to Explore Potential Business Funding Options?

Answer a few preliminary questions to explore potential funding paths that may align with your business profile.
EXPLORE MY FUNDING OPTIONS →
No obligation to review potential options. Available products, amounts, costs and terms depend on the applicable provider and the business’s qualifications.

Independent Broker Disclosure

Round Rock Business is an independent business funding broker and educational resource. Round Rock Business is not a lender and does not make credit decisions, approve applications, determine funding amounts or guarantee that financing will be available.

Applications may be submitted to or processed through independent third-party providers. Each applicable provider establishes its own eligibility requirements, pricing, repayment terms and approval standards. Review all terms and costs carefully before accepting any potential offer.